TL;DR
An accident in a borrowed car and California insurance can raise questions about which policy pays, who is responsible, and what happens when coverage falls short. California law often looks first to the car owner’s policy, but permission, policy exclusions, and the driver’s own insurance can change the outcome.
Borrowing a car sounds simple. Your friend hands you the keys, you run an errand, and you bring it back. What could go wrong?
Quite a lot, as it turns out. One crash can leave you dealing with medical bills, car repairs, insurance disputes, and a difficult conversation with someone you care about.
At Blair & Ramirez LLP, we understand that accident claims can feel overwhelming when you do not know where to turn. Knowing how California law treats borrowed vehicles can help you understand your rights, your responsibilities, and the questions to ask when an insurance company gets involved.
Which Insurance Pays When You Crash a Borrowed Car?
Here is the basic rule. When someone borrows your car with permission and causes an accident, the owner’s auto insurance often provides the first source of liability coverage. California law also requires coverage for qualifying permissive drivers under Insurance Code section 11580.1, subject to the law’s terms and exceptions.
But does that mean every borrowed-car accident falls under the owner’s policy? No. The policy’s terms, the driver’s permission, and the kind of loss all matter.
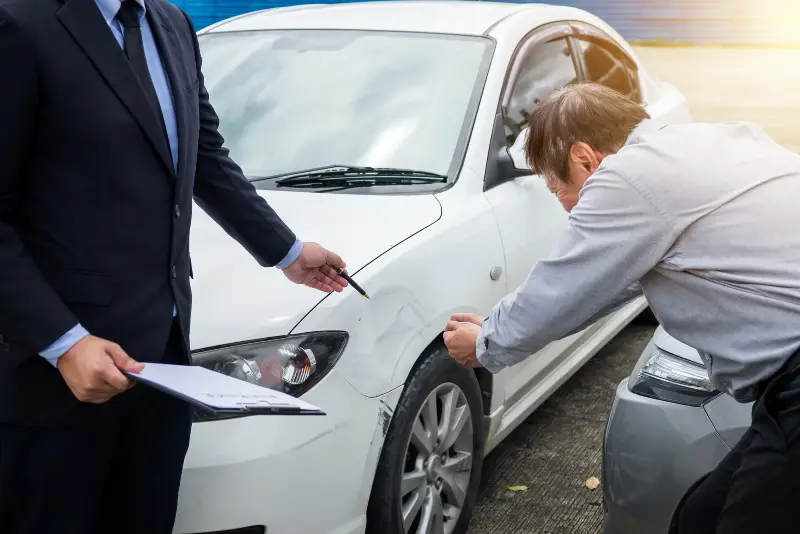
Consider a friend who borrows your sedan to pick up groceries and rear-ends another vehicle. The owner’s liability policy may cover injuries and property damage caused to others. Damage to the borrowed sedan itself falls under a different question, usually involving collision coverage or another applicable provision.
The California Department of Insurance offers guidance on auto insurance and coverage options.
| Situation | What to check |
| The driver had permission | The owner’s liability policy and its coverage terms |
| The driver damaged the borrowed car | Collision coverage, deductibles, and exclusions |
| The driver has their own auto policy | Whether that policy provides additional or excess coverage |
| The driver used the car for paid work | Business-use or delivery-related exclusions |
| The driver took the car without permission | Coverage terms and the facts surrounding the unauthorized use |
Every claim depends on its facts and policy language. Do not assume that the first insurer you contact will pay every expense.
Permissive Driver Insurance Coverage Depends on Permission
Permission sounds like a simple yes-or-no question. In practice, it can become a major point of dispute.
Did the owner agree to lend the car? Did the owner allow the borrower to drive it only to a nearby store? Could the borrower let another person take the wheel?
California Vehicle Code section 17150 addresses an owner’s liability when someone operates the vehicle with the owner’s express or implied permission. The statute provides the legal starting point.
The California Judicial Council’s Civil Jury Instruction 720 explains the elements of an owner’s liability for permissive use. A claimant generally must show that the driver acted negligently, the defendant owned the vehicle, and the owner gave permission.
Now consider a different situation. Your friend lends you the car for an afternoon, but you let your cousin drive it home. The owner’s permission and the circumstances surrounding that decision become important. The jury instruction explains that a second driver may qualify as a permissive user in certain circumstances when the original borrower authorizes that person to drive.
Permission does not settle every insurance question, though. A policy can contain terms that affect coverage, and liability for an accident remains a separate issue from the insurer’s duty to pay.
Who Pays If a Friend Crashes My Car?
The answer depends on who caused the crash, what insurance applies, and whether the owner bears any independent responsibility.
California Vehicle Code section 17151 limits certain forms of an owner’s statutory liability to $15,000 for injury or death to one person, $30,000 for injury or death to multiple people in one accident, and $5,000 for property damage. These limits apply to the statutory owner liability covered by that section, not automatically to every claim against the owner.
| Potential source | What it may cover |
| Car owner’s liability insurance | Covered injuries and property damage caused to others |
| Borrower’s auto insurance | Additional or excess coverage, depending on the policy |
| Collision coverage | Covered damage to the borrowed vehicle |
| Uninsured/underinsured motorist coverage | Eligible losses when the at-fault driver lacks enough qualifying insurance |
| The responsible driver’s personal assets | Potential damages beyond available insurance, subject to applicable law |
The details matter. If your friend caused the crash, the owner’s policy may respond first. If another driver caused it, that driver’s liability insurance may be responsible instead.
A recent case shows why insurance details deserve careful attention. In Murphy v. AAA Auto Insurance of Southern California, the Court of Appeal upheld the denial of a claim under a policy exclusion for carrying property for compensation. Murphy had been driving his own car while making paid deliveries.
The court did not decide a borrowed-car dispute, but the case illustrates a practical point: an auto policy’s exclusions can matter as much as its general promise of coverage.
Past legal decisions do not guarantee or predict a similar outcome in future cases. Each case is different and must be evaluated on its own facts and circumstances.
Owner Liability for a Borrowed Vehicle Can Go Beyond Insurance
Does lending your car automatically make you responsible for everything the borrower does? No. But California law recognizes circumstances in which a vehicle owner can face liability.
The first is statutory liability for a driver’s negligent operation with the owner’s permission. The second involves the owner’s own conduct.
That distinction matters when someone lends a car to a person they know cannot drive safely. Suppose a vehicle owner hands over the keys to a friend whose license has been suspended, who has repeatedly driven while intoxicated, or who cannot safely operate the vehicle. If that decision contributes to a crash, the owner could face a claim for negligent entrustment.
California’s Civil Jury Instruction 724 outlines the elements of negligent entrustment of a motor vehicle. The claimant generally must show that the driver acted negligently, the owner or qualifying possessor entrusted the vehicle to the driver, the owner knew or should have known the driver was unfit, and that unfitness substantially contributed to the harm.
The distinction is important because California’s statutory limits on ordinary owner liability do not automatically cap liability for the owner’s own negligence. The facts must support that separate claim.
What Recent California Car Crashes Teach Us About Liability
Recent crashes involving public figures can draw attention to the consequences of dangerous driving. They cannot, by themselves, answer a borrowed-car insurance question.
In September 2026, James Wehr, a co-founder of the South OC Cars and Coffee community, died in a crash involving a McLaren in Irvine. Another occupant, Alexis Helena Kramer, also died. According to the Los Angeles Times, police said the car traveled at high speed, lost control, struck a tree, and caught fire. Authorities had not identified the victims in the initial report, and the investigation remained a separate matter from any determination of civil liability.
Read the Los Angeles Times report.
The available reporting does not establish that Wehr borrowed the car or resolve any insurance question. It would be misleading to suggest otherwise. Still, the tragedy underscores why drivers should understand a vehicle’s insurance and use restrictions before getting behind the wheel.
A different case illustrates the legal stakes more directly. In February 2025, authorities arrested influencer Summer Wheaton in connection with a fatal 2024 collision on Pacific Coast Highway in Malibu. The Los Angeles Times reported that she faced charges related to the crash, which killed rideshare driver Martin Okeke. The allegations and criminal charges must not be treated as a final finding of guilt.
Neither report establishes a borrowed-car dispute. Their relevance is limited to the wider questions that arise after a serious crash: who drove, what caused the collision, which insurance policies apply, and whether the evidence supports a civil claim.
Frequently Asked Questions
Key Takeaways
- The owner’s auto policy often provides the first source of liability coverage when a borrower has permission to drive.
- The driver’s own insurance, the owner’s policy exclusions, and the type of damage can affect which policy pays.
- California Vehicle Code sections 17150 and 17151 address certain forms of owner liability and statutory limits.
- Negligent entrustment can create a separate claim when an owner knowingly lends a car to an unfit driver.
- Police reports, photographs, witness details, insurance documents, and the terms of the owner’s permission can all help clarify a claim.
Know Your Options Before an Insurance Dispute Grows
A borrowed car should not turn an ordinary day into months of confusion over insurance, medical bills, and responsibility. Yet that is exactly what can happen when the driver, owner, and insurers disagree about permission or coverage.
Blair & Ramirez LLP can help people understand their options after an accident, review the issues that affect a personal injury claim, and determine what steps may be appropriate based on the facts. If you have questions about a borrowed-car accident, reach out to us today to request a consultation or ask about a free case review.
Understanding your rights is a practical first step toward making informed decisions about what comes next.